Key Takeaways
- Business interruption insurance can provide essential financial support for entrepreneurs during unexpected disruptions.
- Choosing the right mix of coverage options requires understanding your unique business risks and insurance policy details.
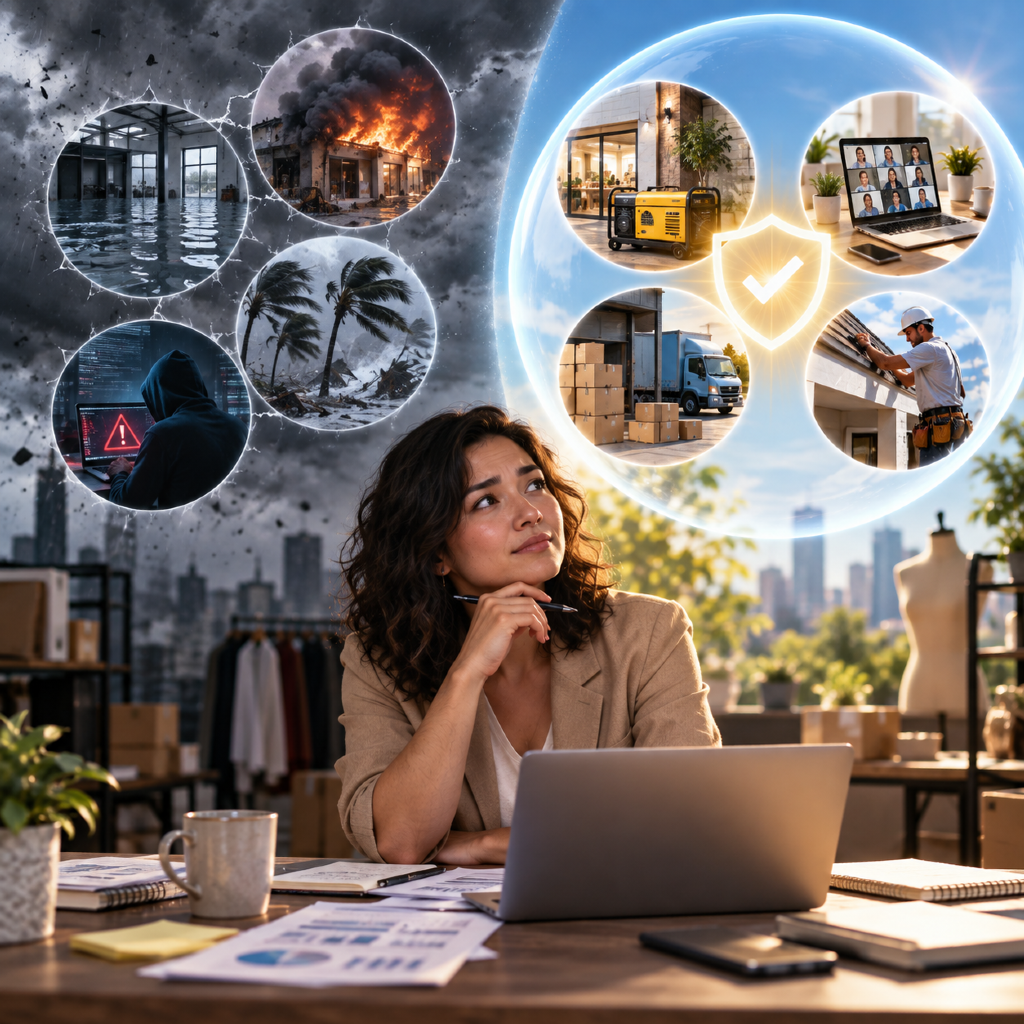
Many small businesses never reopen after a major disruption—making the right insurance decision critical for longevity in 2026. As an entrepreneur, ensuring business continuity means looking beyond basic policies. Let’s break down the essentials of business interruption insurance versus other coverage options, so you can confidently protect your service-based venture.
What Is Business Interruption Insurance?
How It Protects Entrepreneurs
Business interruption insurance is designed to cover income loss when your operations are temporarily halted due to covered events. Unlike property insurance, which focuses on repairing or replacing physical assets, this coverage addresses the income you might lose and essential operating expenses during the downtime. For entrepreneurs—especially those running service-based businesses—this can mean staying afloat while you recover, pay employees, or cover ongoing costs until normal activity resumes.
Common Coverage Scenarios
Typically, business interruption insurance kicks in when a covered peril, such as fire, storm damage, or certain types of theft, makes your workspace unusable. Eligible coverage often includes payroll, rent, utilities, and sometimes even taxes or loan payments. The specific scenarios and covered causes of loss will depend on individual policy language, so it’s crucial to review those details with your provider.
Which Coverage Options Do Entrepreneurs Have?
Property Insurance Overview
Property insurance is foundational for most businesses, insuring the physical location, equipment, furniture, or inventory against damage or loss caused by risks like fire, vandalism, and weather events. While this protection restores your assets, it does not compensate for lost income or help you cover ongoing expenses during a closure.
Extra Expense Coverage Explained
Extra expense coverage goes a step further by reimbursing costs associated with minimizing downtime after a disruption. For instance, if you need to temporarily relocate to keep serving clients, this coverage can handle added rent or equipment leasing fees. It is frequently offered as an add-on to business interruption insurance, making your plan more robust and responsive to complex, real-world interruptions.
How Does Business Interruption Insurance Work?
Triggering Events For Claims
Not every setback triggers a business interruption claim. Covered events are typically those listed in your property policy—such as fire, major water damage, or windstorm. Events must cause direct physical loss that leads to suspended or reduced operations. Routine maintenance or voluntary closures do not qualify.
Claim Settlement Process
When disruption occurs, you’ll notify your insurer as soon as possible. The process usually involves documenting lost income based on pre-interruption financials, receipts for ongoing obligations, and proof of physical damage. Once your claim is submitted, a claims adjuster will evaluate the extent and duration of the loss to determine your benefit. Payments are generally made to cover net profits you would have earned, plus necessary fixed costs, up to your policy limits and within the agreed-upon indemnity period.
What Are Key Differences Between Options?
Scope and Limitations
Business interruption insurance focuses on your lost revenue and ongoing expenses, while property insurance restores physical assets. Extra expense policies support the additional costs necessary to resume operations quickly. Importantly, business interruption does not usually cover losses due to market changes, pandemics, or utility failures unless explicitly stated. Each option has its own limitations, waiting periods, and exclusions.
Cost Considerations
The cost of business interruption insurance is influenced by your business type, gross revenues, chosen coverage period, and physical risk factors. Property insurance costs are driven by the value and condition of assets, location, and security measures. Adding extra expense coverage increases your premium, but may offer enhanced peace of mind. It’s wise to review your budget and risk profile annually to ensure the right fit without over-insuring or exposing yourself to costly gaps.
Pros and Cons for Service-Based Businesses
Business Interruption Insurance Pros
For service-based entrepreneurs—consultants, coaches, and freelancers—business interruption insurance provides a financial cushion if you can’t deliver client projects or host events due to disruption. It helps pay staff, cover rent, and keep recurring bills in check even when cash flow halts. This can be vital in protecting your brand reputation and customer trust while you recover.
Common Coverage Options Cons
Not all business disruption scenarios are covered. Policies may exclude certain natural disasters, government shutdowns, or pandemics without specific endorsements. Premiums can seem high, and claim documentation can be complex. Property insurance alone won’t reimburse lost revenue, while extra expense coverage requires you to act quickly—and often spend money upfront—to access full benefits. Balancing comprehensive protection with affordability is a key challenge for many entrepreneurs.
How Do You Decide What’s Best for You?
Assessing Your Unique Risks
Start by examining your revenue sources, core processes, and physical and digital dependencies. Ask yourself: How long could you afford to be offline? Do you serve clients from a fixed location, remotely, or a mix? What kinds of disruptions are most likely in your region or industry? Engage with a qualified insurance advisor who understands the nuances of service-based businesses to identify critical gaps and tailor an effective strategy.
Key Questions to Ask Providers
Before purchasing or renewing any policy, ask:
- What specific events does the policy cover (and exclude)?
- How is lost income calculated, and what documentation is required?
- Are there waiting periods before benefits start?
- What is the maximum indemnity period?
- Can extra expense coverage be bundled, and if so, how are payments determined?
- How does the policy treat remote or hybrid work environments?
Getting clear, written answers ensures your expectations match reality if and when you need to file a claim.
Are There Common Misconceptions?
Typical Myths Debunked
Many entrepreneurs believe business interruption insurance covers every unexpected halt. In reality, most policies only respond to physical-peril events—so situations like cyberattacks, supply chain breakdowns, or viral outbreaks often require separate endorsements or specialized coverage. Another misconception is that property insurance automatically includes income coverage; in truth, you need explicit business interruption clauses.
Practical Tips for Entrepreneurs
To avoid costly surprises, regularly update your financial documentation and keep digital and paper copies secure. Make a habit of reviewing coverage annually, especially if your operations change or revenue grows. Develop a business continuity plan that complements your insurance—this double-layered approach reduces risk and bolsters resilience.